Connecticut’s manufacturing sector, anchored by the aerospace and defense supply chain, has a different injury profile than the general commercial economy. That difference can be seen in how the state prices workers’ compensation insurance coverage, as well as in how much control a manufacturer has over the number on the renewal invoice.
Why Connecticut Manufacturing Carries a Distinct Workers’ Comp Profile
The premium a manufacturer pays for workers’ comp insurance is based primarily on three factors: the overall payroll, the frequency and severity of past claims, and the job classifications.
Connecticut’s manufacturing base is different from the national mix, and that difference affects its workers’ comp profile. The state has over 16 times the national average of aerospace jobs, and Connecticut manufactures more than 21% of all aircraft engines and engine parts, accounting for more than 17% of all shipbuilding and repair in the U.S.
Connecticut’s manufacturing economy is weighted toward precision assembly, engine testing, and heavy fabrication in a way most states are not. National manufacturing injury data, however, is one of the factors most states’ workers’ comp programs are priced against, and it is built from a much broader mix that includes food processing, textiles, plastics, and general assembly.
The result is an employee base that makes more per hour than the national average and is also exposed to machinery operation, chemical handling, high levels of noise, and repetitive motion.
Nationally, sprains, strains, and back injuries account for roughly 28% of manufacturing days-away-from-work cases. Cuts, lacerations, and punctures make up another 13.3%, according to the U.S. Bureau of Labor Statistics. Connecticut manufacturers carry those same exposures, then layer on the complexity of high-force precision equipment that comes with aerospace and shipbuilding work.
How NCCI Class Codes Apply Across a Manufacturing Workforce
The National Council on Compensation Insurance (NCCI) is an advisory organization that collects and analyzes workers’ compensation data. With this data, it develops rate recommendations that many states, including Connecticut, use to determine insurance premiums.
In essence, the NCCI separates types of work into class codes and assigns each class code an advisory loss cost that is based on its history of risk. Jobs with histories of frequent or expensive accidents become more expensive to insure. Machine shop work, metal stamping, and aircraft component assembly, for example, will each get a separate NCCI classification and base rate.
A precision manufacturer running stamping presses, a machine shop floor, and final assembly under one roof will need to classify each type of work, and then track the time that each employee spends each week doing that work. If an employee spends time doing work with different job classifications, the company should record how their time is split.
When the policy is up for renewal, the insurer will look at how each employee spent their time working. If the employer can show that someone spent half their time doing a job with a lower rating, that can lower the overall insurance premium.
If that split work isn’t recorded, then auditors will default to using the highest-rated code across an entire job description. That default can push an otherwise well-classified workforce into a materially higher blended rate at renewal.
The Injury Types That Most Often Drive Manufacturing Workers’ Comp Claims
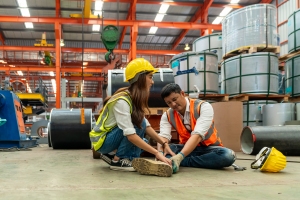
Three claim categories consistently drive workers’ compensation cost across Connecticut manufacturing employers: machine-related lacerations and crush injuries, forklift and material handling incidents, and musculoskeletal strain from repetitive motion. Noise-induced hearing loss is also common.
Machine-Related Laceration and Crush Injuries
Machine-related injuries occur at the point of contact between an operator and a press, shear, or CNC machine. They tend to produce the highest per-claim severity of these three categories because of the force involved.
Material Handling Incidents
Incidents involving forklifts, hoists, and pallet jacks generate steady claim frequency in any facility moving stock or finished components between stations. Injuries typically involve people being struck by or caught between material handling equipment.
Musculoskeletal Claims
Musculoskeletal issues are typically caused by repetitive lifting, awkward assembly postures, or vibration exposure, and build over time. They often become the highest-cost category over a full policy year because of extended recovery and periods of lost time or modified duty.
Noise-Induced Hearing Loss
Noise-induced hearing loss is relatively common in precision and aerospace manufacturing, where machining, riveting, and engine test operations run at sustained high decibel levels. Connecticut General Statutes Section 31-275 treats occupational hearing loss as a possible compensable injury.
Because hearing loss may be classified as an occupational disease or repetitive trauma injury, an employee generally has one to three years from the manifestation of symptoms to file, depending on the situation. A claim filed in the third year can still fall inside the three-year experience period NCCI uses to calculate that year’s E-Mod.
How Connecticut’s Aerospace and Defense Sector Shapes the Risk Picture
Connecticut’s concentration of aerospace, defense, and precision manufacturing means that many facilities have specialized classifications with distinct class codes. And because each classification will have its own base rate, proper classification is an important and sometimes complex process that ultimately affects the premium.
An employee misclassified into a role with a lower base rate can lead to an audit adjustment and penalties, and can also complicate the claims process should they have an accident. An employee misclassified into a role with a higher base rate falsely inflates the insurance premium. Depending on the amount of the overcharge, when it was found, and your carrier, you may receive a credit.
Defense contractors and their supply chain partners might also have increased obligations to keep records and other documentation tied to federal contract requirements. These are in addition to Connecticut’s baseline statutory requirements, and particularly involve subcontractor coverage verification and certified payroll reporting.
Those extra requirements might not show up until a manufacturer is already deep into a defense contract. A company moving from commercial work into defense subcontracting should confirm what its specific contract requires rather than assume its existing compliance structure is adequate.
What Connecticut Manufacturers Can Do to Control Workers’ Comp Cost
A documented safety program, a written return-to-work policy offering modified duty, and proactive claims management starting at first report of injury each move the experience modification calculation in a measurable way over the three-year evaluation window.
Modified duty affects the math directly. An employee who has returned to work, even on light duty, stops accumulating temporary total disability payments, which count as losses in the mod formula. In contrast, a claim left open without a return-to-work option can continue generating cost long after medical treatment has ended.
Reviewing class code assignments at policy renewal can also help control workers’ comp costs. A workforce that spans stamping, machining, assembly, and shipping, as well as office and administrative work, is complex and likely to carry payroll allocation errors.
Review Your Manufacturing Workers’ Comp Program With JMG
Connecticut manufacturers can work to control their insurance costs by combining accurate classification, a documented safety culture, and consistent claims follow-through. Especially if your facilities have a complex workforce in specialized roles, working with an experienced broker can help make sure your workforce is properly classified before your next policy renewal.
JMG Insurance Corp was founded in 1916 in Fairfield County, Connecticut. We’ve seen how the aerospace, shipbuilding, and defense industries have shaped manufacturing in the past century, and we’ve been helping companies manage their insurance needs.
Contact JMG Insurance Corp to review your current class code assignments, confirm your experience modification calculation, and identify where your program could be structured more effectively.