 Essential Takeaways:
- Construction workers are at greater risk of injury from falls, equipment, and electrical hazards.
- Workers’ compensation insurance covers medical treatment, lost wages, rehabilitation, and death benefits.
- Premium costs are tied to payroll, job classification, and claims history.
- Subcontractor coverage gaps and worker misclassification can lead to major liability exposure.
- A documented response plan reduces claims complications and total claim costs.
Construction work is one of the most physically demanding fields and poses serious hazards. Between operating heavy machinery, handling electrical systems, and working at heights, there are countless opportunities for danger. Unfortunately, even seemingly minor on-the-job accidents can sideline a skilled worker for weeks or months. On top of that, these accidents can compromise a business’s finances and put it under unwanted regulatory scrutiny.
Most states require workers’ compensation insurance for construction workers, but it is also smart from a financial standpoint, thanks to the financial protection it provides employers and workers alike. Here is a look at how it works and how you can manage site risks to minimize accidents.
Why Construction Workers Have a Higher Injury Risk Than Most Other Industries
Construction work is very physical, so it is only natural that workers are vulnerable to repetitive motion injuries. Still, that’s only one aspect to consider. OSHA points to four major factors behind construction-related fatalities. Known as the “Fatal Four”, they are electrocutions, caught-in/between accidents, falls, and struck-by incidents.
While these incidents are never welcome, for smaller contractors with lean crews, the effects go beyond the worker involved. It can cause a project to come to an abrupt halt, trigger OSHA inspections, and result in considerable financial losses that could take years to recover from.
Small construction businesses are particularly vulnerable because they typically lack the safety infrastructure and internal HR teams that larger companies can afford. This is why it is especially pressing for them to obtain the right workers’ comp insurance coverage and manage it properly.
What Workers’ Compensation Insurance Actually Covers on Construction Jobs
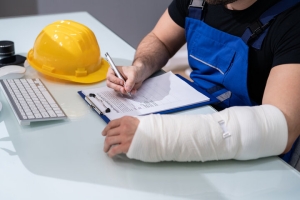 Workers’ comp coverage kicks in when an employee is injured or becomes ill as a direct result of their work. For construction sites, this can mean anything from acute injuries such as lacerations, lifting-related back injuries, and broken bones to long-term conditions such as occupational illnesses from dust or chemical exposure and repetitive stress injuries.
A standard workers’ compensation policy will cover:
- Medical treatment, including emergency care, surgical operations, and physical therapy
- A portion of lost wages while the worker is unable to return to their job
- Vocational rehabilitation in cases where the worker needs to be retrained for a different role
- Death benefits for the worker’s family in the event of a fatal accident
Workers’ compensation operates on a no-fault basis. This means that the benefits are available regardless of who caused the accident. At the same time, however, employees who receive workers’ comp benefits generally cannot sue their employer directly for work-related injuries. It is essentially a type of two-way protection.
How Small Contractors Can Keep Premium Costs Under Control
Premium costs are calculated based on total payroll, employees’ job classification codes, and the company’s claims history. Riskier classifications, such as roofing, structural steel, or excavation work, naturally have higher base rates than less hazardous roles.
Nevertheless, small businesses can take some steps to control their insurance costs. For example, following a written safety program, providing proper equipment and training, and conducting regular site inspections can all reduce claims. Fewer claims mean a lower experience modification rate (e-mod), which keeps premiums down.
Accurate payroll reporting is also essential, as underreporting payroll or misclassifying workers to lower premiums creates audit liability and can lead to dangerous gaps in coverage.
Coverage Mistakes That Leave Small Construction Businesses Exposed
Some of the most expensive insurance issues encountered by construction companies aren’t related to injuries. Instead, they stem from coverage gaps that do not become apparent until after the claim has been filed.
One common problem is failing to verify that the subcontractors you work with have their own workers’ compensation insurance. If these individuals get hurt while working on your job site and do not have coverage, your policy could be responsible for the claim. Therefore, it is advisable to obtain and verify insurance certificates from all subcontractors before working with them.
Another common issue is worker misclassification. Make sure that everyone performing hands-on construction work is properly classified. All classifications must be chosen based on the work the employee actually performs.
What To Do When a Construction Worker Gets Hurt on the Job
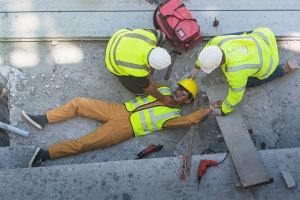 It is smart to establish a clear response plan for injuries. The first step when a worker is injured is to seek appropriate medical care; make sure you know which providers have been approved in advance.
After that, it is imperative to document the incident in writing, report it to your insurance carrier right away, and cooperate with every step of the claims process. Keep in mind that even a basic return-to-work program can help keep your insurance costs down over time.
Let’s Review Your Coverage
If you run a small construction business and aren’t sure whether your workers’ comp policy matches your actual site risks, reach out to John M. Glover Insurance Agency. We’ll take the time to understand your operation and make sure you, your crew, and your business are properly protected.