Essential Takeaways:
- Outdated electrical systems, such as knob-and-tube wiring, are a top reason carriers decline coverage.
- Aging or damaged roofs can cause policy denials.
- Your flood zone location significantly affects standard policy eligibility.
- Foundation and structural problems can raise red flags with underwriters.
- Oil tanks, especially buried ones, create environmental liability that most carriers won’t accept.
Connecticut is a highly desirable place to own a home, thanks to its charming colonial architecture and scenic coastal views. However, there is also another reality many homeowners must address: some properties can be very challenging to insure via standard carriers. Has your home been declined homeowners’ insurance or non-renewed? Most insurability problems can be corrected before they become a crisis.
Why Your Aging Roof Could Get You Dropped
A home’s roof is one of the first things underwriters look at, and those that have significant missing or damaged shingles or are upwards of two decades old could receive a refusal. Connecticut is known for its harsh winters, with freeze-thaw cycles, heavy snow loads, and ice dams all creating significant hazards.
What homeowners can do: Pull any permits on file with the town and document your home’s last roof replacement. If the roof is approaching 20 years old, get a professional inspection and obtain repair estimates before the renewal period.
How Old Wiring Can Stop a Policy in Its Tracks
Connecticut saw a housebuilding boom in the early 1900s, so plenty of homes have wiring not designed for modern electrical loads. For example, knob-and-tube wiring, which was standard through the 1940s and early 1950s, is one of the most serious red flags for insurers. Many insurance companies have restrictions concerning knob-and-tube wiring, particularly when insulation has been placed around the wires, which can lead to overheating.
Homes with this type of wiring can encounter outright policy denials or premiums so high that coverage becomes unaffordable. The same concern applies to aluminum branch-circuit wiring from the 1960s and 1970s, which is associated with connection failures and fire risk.
What homeowners can do: Hire a licensed Connecticut electrician to inspect and document your home’s electrical system, as some carriers may write a policy if an electrician certifies the wiring is in acceptable condition or if the homeowner commits to a rewiring timeline.
What Flood Zones Mean for Standard Coverage
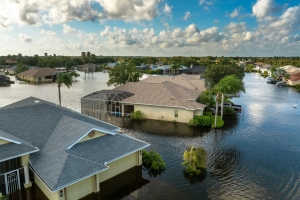
There is a lot of confusion surrounding flood zones, with standard homeowners’ insurance policies normally failing to cover losses stemming from flood damage. However, for homes in FEMA-designated flood zones, coverage may be denied altogether.
If a home sits in a federally mapped flood plain, mortgage lenders require flood insurance as a condition of the loan. Unfortunately, flood maps are occasionally redrawn, which can cause a home to sit in a floodplain for the first time or shift into a more hazardous zone, both of which result in higher premiums.
What homeowners can do: Check FEMA’s flood map service center to confirm your zone and consider whether separate flood coverage through the National Flood Insurance Program or a private flood carrier is right for you.
Foundation Problems That Make Underwriters Balk
The structural integrity of your home is a major concern for insurance carriers. Horizontal cracks and uneven floors signal deep structural problems and could result in inflated premiums or coverage denials.
Connecticut also has a specific, well-documented problem: pyrrhotite, a mineral found in some concrete used to pour foundations in the northeastern part of the state from the 1980s through the early 2000s.
Homes with pyrrhotite contamination show progressive cracking as the concrete expands over time. Carriers may decline coverage for homes with this problem.
What homeowners can do: If your home was built during that window in affected counties, consider investing in a foundation specialist inspection.
Why Oil Tanks Create an Insurance Headache
Buried or abandoned oil tanks are another common disqualifier for homeowners’ insurance in Connecticut. Carriers consider underground storage tanks an environmental liability because a leak could contaminate the surrounding groundwater and soil. The remediation costs for these incidents can significantly exceed the home’s value, so many insurers are unwilling to extend coverage.
What homeowners can do: If your home has a buried tank, have it tested, properly decommissioned, and removed by a licensed contractor. Be sure to keep proper documentation on file.
If Standard Coverage Is Denied, the CT FAIR Plan Is an Option
For homeowners who are unable to obtain coverage in the private market, the Connecticut Property Insurance Placement Facility, also known as the CT FAIR Plan, offers a final option. Its coverage is typically more limited and more expensive than a standard policy, but it does give you a baseline while you work to correct the underlying conditions. However, it should not be considered a permanent solution.
Find Out Exactly Where Your Home Stands
At John M. Glover Insurance Agency, we work with Connecticut homeowners every day to sort through exactly these types of issues. Has your property been declined, is a renewal coming up with concerns, or is your home being purchased with insurability questions? We can help you identify the right options and get coverage in place.
Contact us today to speak with a local agent who understands Connecticut homes and the coverage challenges that they pose.